Dairy markets are increasingly competing on timing rather than supply. Global milk output remains strong, but delayed buying programmes and concentrated demand are tightening availability in specific shipment windows and origins, and product that is compliant, uncommitted and able to arrive on time is earning a growing premium even in markets that look well supplied, CZ App reports.
Key points:
- New Zealand milk collections rose 3.3% in August on a milk solids basis, yet suppliers already report tight whole milk powder (WMP) availability for nearby shipment periods;
- after months of delay, Algeria has issued sanitary derogations to a wider range of importers, creating strong demand for milk powders;
- WMP futures are pricing El Niño weather risk, while physical markets are pricing shipment timing risk;
- Fonterra’s share of New Zealand milk collections may slip by a further 0.3 percentage points this season;
- the key market question has shifted to whether product is available in the right origin and shipment window.
Supply is growing, but availability is uneven
Last month’s analysis looked at why additional milk was not translating evenly into the products buyers needed. That allocation problem remains, but another constraint is now coming into view: even where the right product is being made, it may not be available from the origin or in the shipment window buyers require.
New Zealand milk production remains exceptionally strong, with August collections up 3.3% year on year on a milk solids basis. Fonterra’s intake rose 3.0%, while other processors grew even faster, at 4.4%.
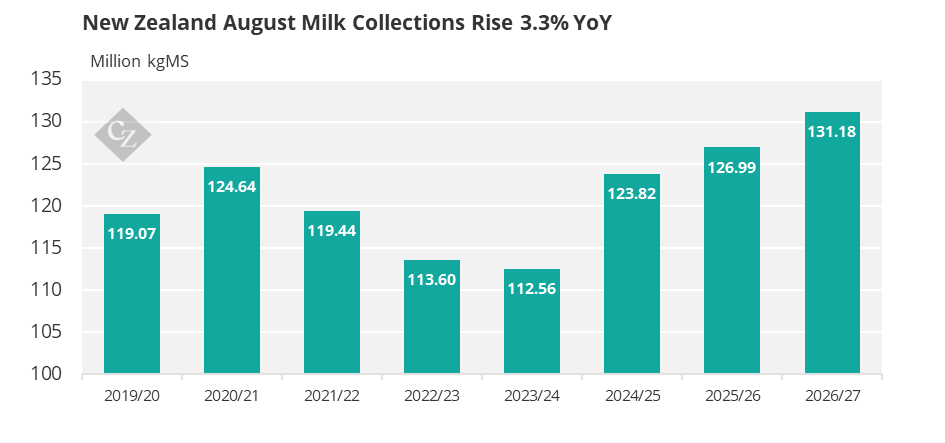
Strong output would normally mean comfortable availability. Yet suppliers are already reporting tight whole milk powder (WMP) availability for some nearby shipment periods — underlining an increasingly important distinction: total production and prompt availability are not the same thing.
Milk can be plentiful while export availability stays tight. Once production is committed to existing contracts or specific manufacturing programmes, volumes available for new business can shrink quickly. Buyers are therefore putting more value on product that can ship within the required window than on product that may become available later in the season.
Algeria returns, and buyers need product sooner
Algeria offers the clearest example. After months of delay, sanitary derogations have reportedly been granted to a broad range of grocery importers beyond the country’s traditional buyers. These import licences had been expected since April, leaving many buyers with little forward cover and generating a strong bid for milk powders, especially WMP.
Attention is now turning to the next tender by ONIL, Algeria’s National Interprofessional Office for Milk and Dairy Products (Office National Interprofessionnel du Lait et des Produits Laitiers). Market participants generally believe ONIL keeps at least around six months of physical stock in the country. With current cover reportedly running only until August 2027, purchasing may soon need to focus on securing arrivals from February onward.
The timing matters. If ONIL targets February–April arrivals, New Zealand suppliers would broadly need to allocate product for December–February departure — precisely when several suppliers are already reporting limited WMP availability.
ONIL and newly licensed private buyers could thus end up competing for the same relatively small pool of prompt product, allowing nearby shipment periods to command a premium over later-season supply.
Time becomes a competitive advantage
For New Zealand exporters, the challenge is increasingly time rather than production cost alone. The country remains one of the world’s most competitive dairy producers, backed by strong pasture-based systems and another healthy season, but buyers in Africa and other import-dependent regions are growing more sensitive to arrival timing and shipment certainty.
That changes how dairy products are valued. The most attractive offer is not necessarily the cheapest tonne, but the tonne that can arrive within the required delivery window while meeting local import requirements.
As delayed demand returns, logistics and timing are becoming bigger drivers of value, and uncommitted product available for prompt shipment is growing scarce despite strong underlying milk output.
Futures price weather risk, physical markets price timing risk
Another notable divergence is emerging between futures markets and physical trade.
WMP futures on the Singapore Exchange (SGX) are building a substantial premium into later delivery months, reflecting market concern about possible late-season El Niño-related production risks.
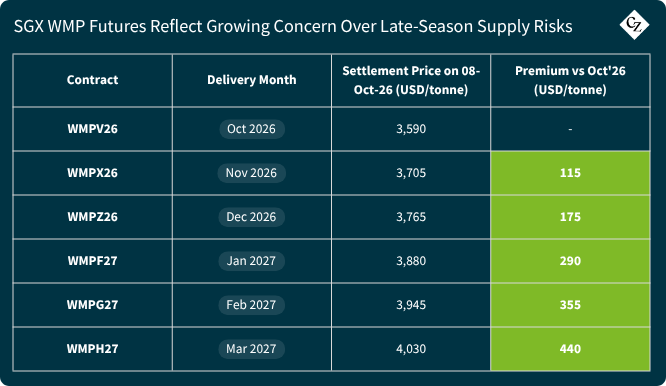
However, strong opening milk flows, favourable pasture conditions, ample feed and supportive milk prices may help farmers defend production if conditions turn drier.
The market is therefore pricing two separate risks: futures focus on future production uncertainty, while physical markets respond increasingly to near-term shipment availability and concentrated buying. The curve is pricing future production risk at the same time as prompt physical availability may tighten for entirely different reasons.
Structural change beneath the surface
New Zealand’s strong milk output is accompanied by continued shifts in processor market share.
Fonterra appears set to lose a further 0.3 percentage points of collection share this season. Its share has been declining for much longer, though the pace has held steady at around this level for just over two years. The annual changes are modest, but they highlight an increasingly competitive market for milk supply.
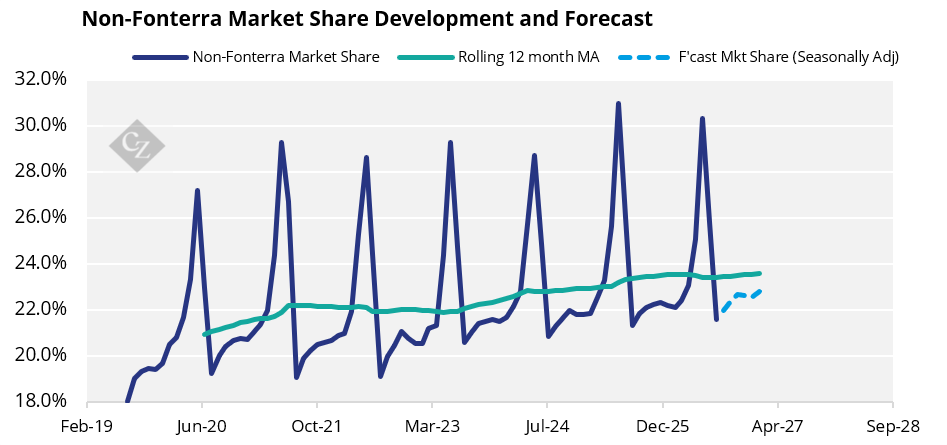
Regional conditions are also becoming more mixed. Soil moisture data show parts of the North Island drying faster than normal for the season, while the South Island remains relatively wet. Conditions do not yet threaten production but warrant monitoring as the season progresses.
Elsewhere, changing trade relationships may reshape product flows. The proposed free trade agreement between the European Union (EU) and the Philippines could alter sourcing decisions in Southeast Asia, creating both new opportunities and competitive pressure for exporters.
Demand signals are not always where markets expect
Discussion of Chinese dairy demand remains focused on weakness, yet weak demand can still coincide with tight local supply.
Market reports indicate that at least one major Chinese supplier had sold out of both skim milk powder (SMP) and WMP by early October. This is not evidence of a broad recovery in consumption; rather, it shows how limited local availability can create pockets of apparent strength even when underlying demand is subdued.
Butter markets are also diverging. Global Dairy Trade (GDT) butter prices appear to be levelling off, while premiums for New Zealand-origin butter outside the auction platform are reportedly widening. The growing gap suggests that softer auction prices are not feeding evenly into executable physical offers, especially where buyers need a specific origin or shipment period, despite generally comfortable supply.
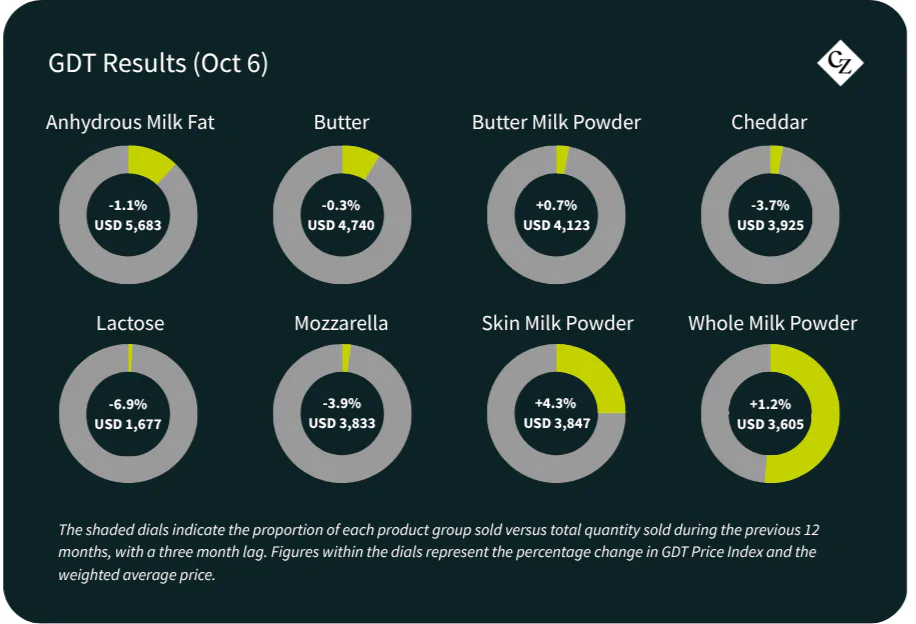
Together, these examples reinforce a broader theme: aggregate supply tells only part of the story. Timing, origin and product availability increasingly matter just as much.
The market question has changed again
Last month, the key question was whether higher milk production was being turned into the dairy products buyers needed. Today, the more important question may be whether those products are available from the right origin and in the right shipment window.
Algeria’s return shows how delayed demand can collide with limited prompt availability, even when milk output is strong and global supply looks comfortable. Buyers are increasingly competing for product that is compliant, uncommitted and able to arrive on schedule.
Dairy markets may no longer be defined mainly by shortages of milk or product, but by the value of timing. Having the right product in the right place matters — but the ability to deliver it at the right moment may be becoming even more valuable.
Source: CZ App